Category: States

Message from MO DOR: HoH and Qualifying Widow(er)

08 Mar 23
Craig Smith
No Comments

Software vendors received the below message from MO DOR this morning.

“Good Morning,

Missouri DOR recently issued letters to Missouri taxpayers who filed with a Head of Household or Qualifying Widow(er) filing status from 2018 -2021, regarding a credit for 2022 Individual Income Tax. DOR’s Income Tax Bureau has provided me the information below to send out, so the software developer community is aware of this and able to address customer inquiries regarding the letters. As noted below, the credit will automatically be applied by DOR and does not need to be claimed on the 2022 MO return.

On Dec. 22, 2017, the federal government passed the Tax Cut and Jobs Act. This act made significant changes to the federal tax code, including the removal of personal exemptions and dependent deductions. As the state of Missouri bases the income tax calculation on an individual’s federal income tax return, the Missouri Department of Revenue made similar changes beginning with the 2018 tax year, by removing a number of exemptions and deductions from the calculation of the Missouri income tax. 

The Department has performed a subsequent review of Section 143.161.2 RSMo, with reference to the removal of the $1,400 personal exemption provided to individuals using the filing status of Head of Household or Qualifying Widow(er). The Department has determined to reestablish the personal exemption on the 2022 individual income tax return and to retroactively apply the exemption to tax years 2018 through 2021 to eligible filers.

If the application of the additional exemption for eligible filers resulted in an overpayment for years 2018 through 2021, the Department applied those amounts as a credit on the 2022 income tax period. When taxpayers file their 2022 income tax return, the credit(s) will automatically be applied to the income tax return.”

TaxSlayer Pro Online: Printing Issue Related to NC Estimated Payment Vouchers [RESOLVED]

02 Mar 23
Craig Smith
No Comments

3/24/2023: This has been resolved.


3/6/2023: We are still receiving reports of sporadic printing issues for NC with estimated payment vouchers added. We have opened a new high priority work item (Issue 9563)


3/6/2023: The fix is live.


The fix is scheduled to be deployed the morning of Monday, March 6th.


Our development team is aware returns with a NC return added (more specifically with Form NC-40, Estimated Payment Vouchers) are continuing to experience printing issues. We will update this post as additional information is available. If you have returns impacted at your site, we have a couple recommendations that may help depending on what you are trying to do.

Note: E-filing NC returns with estimated payment vouchers is not impacted.

If you are trying to quality review an impacted return, remove the estimated payment vouchers. The same is true to provide a copy of the return to the taxpayer. Obviously the taxpayer needs the payment vouchers, otherwise they wouldn’t be added to the NC return. Once our issue is resolved, we recommend utilizing the Customer Portal to provide a copy of the return to the TP with the vouchers. Another option is to try to print the return from other areas of the application such as:

  • Summary/Print page
  • State PDF View from the State Section grid
  • Submission page of e-file
  • Client List
  • Client Status

Reporting Minnesota Frontline Worker Pay

28 Feb 23
Craig Smith
No Comments

How does it work in TaxSlayer? Inside the Subtractions from Income menu at the bottom, preparers will answer the below question YES or NO. Based on the selection, the program will automatically calculate the appropriate subtraction for the return. If any adjustments are needed, MN has indicated those adjustments will occur on their end after the return has been e-filed and accepted. Prior behavior for this subtraction allowed the preparer to manually enter the appropriate subtraction value in the return. This manual entry resulted in erroneous MN Reject Code 0628: “Severity: ErrorM1M line 29 must not be more than 488 for single, HOH or MFS, and no more than 976 for MFJ. Xpath: M1M Line 29: ReturnState/ReturnDataState/SchM1M/FrontLineWorkerPayAmt“.

Due to the reject code being issued, the entry behavior was updated to be an automatic calculation instead.


Frontline Worker Pay was signed into law on April 29, 2022. Over 1 million Minnesota workers qualified for the $487.45 payment. Federal Forms 1099 were not issued for these payments. The Minnesota Department of Revenue discovered that taxpayers reported this payment incorrectly on 97% of current tax returns filed. As a reminder, this payment is federally taxable and must be reported on line 8 of a taxpayer’s federal Schedule 1 (Form 1040).

The payment is not taxable for Minnesota returns. If the payment is:

  • Reported on line 8 of Schedule 1, also enter this amount on these lines:
    • Line 29 of Schedule M1M, Income Additions and Subtractions
    • Line 10 of Form M1PR, Homestead Credit Refund (for Homeowners) and Renter’s Property Tax Refund
    • Line 5b of Schedule M1ED, K-12 Education Credit
  • Not reported on line 8 of Schedule 1, do not include the payment on the lines above.

Entering Frontline Worker Pay properly on both the federal and Minnesota returns will ensure Minnesota adjusted gross income is calculated correctly.

Message from New Mexico: Error Code 366

22 Feb 23
Craig Smith
No Comments

Software vendors received the below message from New Mexico. Impacted returns can be resubmitted today.


We are aware that a number of vendors have noted receiving rejections, for PIT TY22 filings, with error code 366: “Schedule PIT-ADJ, line 23. Amount cannot exceed $10,000.” We understand that this has prevented the submission of returns, filed as Married Filing Jointly, where both primary and spouse are claiming the armed forces exemption and where the amount on PIT-ADJ line 23 is $20,000. After review, we have revised this business rule to allow returns filed as Married Filing Jointly to claim $20,000 on PIT-ADJ line 23. All other filings will continue to have the $10,000 limit for this exemption. This correction will be available in our production environment as of the morning of 2/22/23, and you may resubmit any returns incorrectly rejected with error code 366 after that time.

We apologize for any confusion resulting from this issue, and we appreciate the outreach by those of you who first noted the problem.

Message from GA DOR: Delay in Acknowledgements

21 Feb 23
Craig Smith
No Comments

Software vendors received the below messaging from GA DOR.

“FYI – We are experiencing a delay in acknowledgements being sent.  Thank you in advance for your patience as we work to resolve this issue.”

IL Subtractions from Income Not Working [RESOLVED]

20 Feb 23
Craig Smith
No Comments

2/22/23 – This is now resolved.


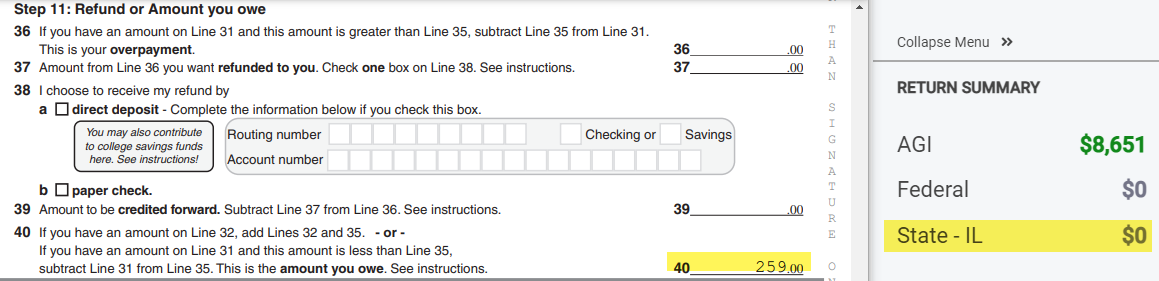
Update 2/20/23: The deployment on Friday, February 17th corrected the calculation issue related to Line 5 of the IL-1040. However, the display in the PDF is still incorrect and does not reflect the accurate refund/amount owed on Line 37 or 40. The Return Summary (example below) is correct and that is the value the TP can expect to owe or receive as a refund. NOTE: The electronic submission is correct and the amount reflected in the Return Summary is what is sent with the electronic submission. It is ok to resume electronically filing impacted IL returns.

So, looking at the screenshot below, the PDF (IL return) incorrectly shows the TP owes $259 (Line 40 of IL-1040). Their Return Summary correctly reflects the TP does not have a tax liability and will not receive a refund from IL.


Update 2/17/23: The fix was rolled back due to an unforeseen issue.  We are currently working to resolve this issue.


The fix for this should be deployed Friday morning, February 17th.


We are aware of an issue that began this morning (2/15/23) where entries in the subtractions from income menu within the Illinois application are not carrying to the return. We have a high priority ticket in with our development team.

Minnesota Reject Code 0628 for Frontline Worker Payments (UPDATE)

16 Feb 23
Craig Smith
No Comments

2/16/23 – 3:30pm ET: MN has indicated they have corrected the erroneous reject and any impacted MN returns can be resubmitted at this time.


We have confirmed with MN that Reject Code 0628 is being issued in error. If you have an impacted MN return, please hold the return until this post is updated indicating that you can resubmit those returns. Details of the reject are below.

“Severity: ErrorM1M line 29 must not be more than 488 for single, HOH or MFS, and no more than 976 for MFJ. Xpath: M1M Line 29: ReturnState/ReturnDataState/SchM1M/FrontLineWorkerPayAmt“

Connecticut Returns That Validated After E-file – Please Resubmit

15 Feb 23
Craig Smith
No Comments

If any CT returns at your site(s) received the below validation error, simply go back into the returns and resubmit from the Submission page. There is no change to the calc on the returns, only elements being included in the e-file in error. This has been corrected and impacted returns can be resubmitted. To see if your site has any validated CT returns, access the “Reject Clients” menu and change the dropdown to reflect Validation Errors. You can also run the State Non-accepted Returns report or State Acknowledgements report.

“Error = The element ‘SchCTIndUseTax’ in namespace ‘http://www.irs.gov/efile’ has incomplete content. List of possible elements expected: ‘StateUseTax’ in namespace ‘http://www.irs.gov/efile’.“